If you need brain surgery, you don’t go to a general surgeon. You go to a neurosurgeon who specializes exclusively in brain surgery. Why? Because there’s a big difference between someone who does “something similar” and someone who does nothing but exactly what you need.
And while we all know the above to be true, it seems all too easy to overlook. Ironically, one of the places people often overlook this fact is in insuring the very healthcare professionals from our example.
When you really need it done right, you need to use a true specialist.
Definition of a True Specialist
The insurance industry uses the word “specialist” far too loosely. In many cases, it is used to simply describe someone who writes a decent amount of a specific line of coverage or class of business. But there’s a major difference between someone who “can” do something and someone who does it every single day. And when it comes to particularly technical and/or volatile classes of business and/or lines of coverage, such as healthcare professional liability (HPL), that definition falls woefully short of describing the level of dedication and expertise needed to actually be a true specialist.
So, what is a true specialist when it comes to insurance?
A true specialist is someone who operates entirely within their niche. Not 60%, not 70%, not 80% or even 90%. A true specialist is someone who spends all of their time focused exclusively on their field of expertise. Day in and day out. Every submission, every risk profile review, every coverage discussion, every underwriting conversation, every claim review, every carrier relationship, every market shift. Their entire professional world revolves around only one thing.
Just like the specialized brain surgeon’s entire career exclusively revolves around brain surgery, a true HPL specialist’s entire career exclusively revolves around healthcare risks.
Why Being a True Specialist Matters
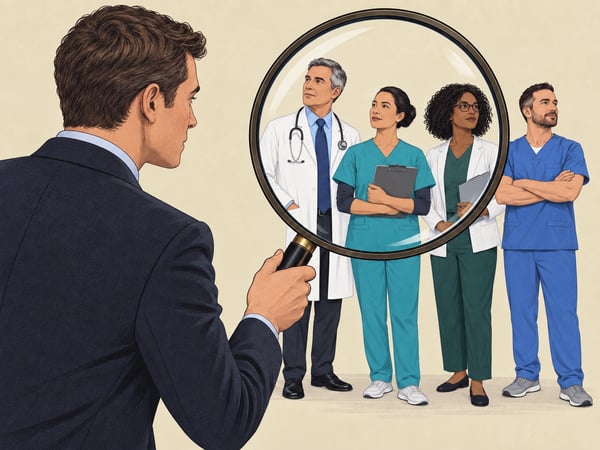
There are over 150 classes of business that need professional liability insurance. Most fall into a general, catch-all category and are provided a basic professional liability product commonly referred to as Miscellaneous E&O. But a very few of those classes of business are different enough, volatile enough and dangerous enough to require their own distinct professional liability product. HPL is one of them.
With HPL, a claim typically starts with the assertion that a patient has been injured as a result of the provision of medical services. The defendant, on the other hand, is typically a highly trained medical provider, with years of education and experience under their belt. Combine the two and you can begin to see why even the smallest of healthcare risks are capable of generating large claims.
HPL needs to be placed correctly, every time—especially when it comes to surplus lines placements. To do that you need to work with a wholesaler who is a true HPL specialist.
Retail Insurance Agents Don’t Need to be Specialists
In reality, most retail insurance agents are not HPL specialists. After all, retail agents are often responsible for serving clients across multiple industries and lines of coverage. That breadth of knowledge and experience is part of what makes them valuable to their customers and to their communities.
But when it comes to healthcare risks, and especially those placed in the surplus line arena, the complexity of the various risk profiles, the level of underwriting scrutiny, and severity of potential claims increase significantly. That is why the wholesale partner you choose becomes critically important.
If you are not an HPL specialist, then your wholesaler absolutely needs to be.
The Benefits of Using a True Specialist Wholesaler
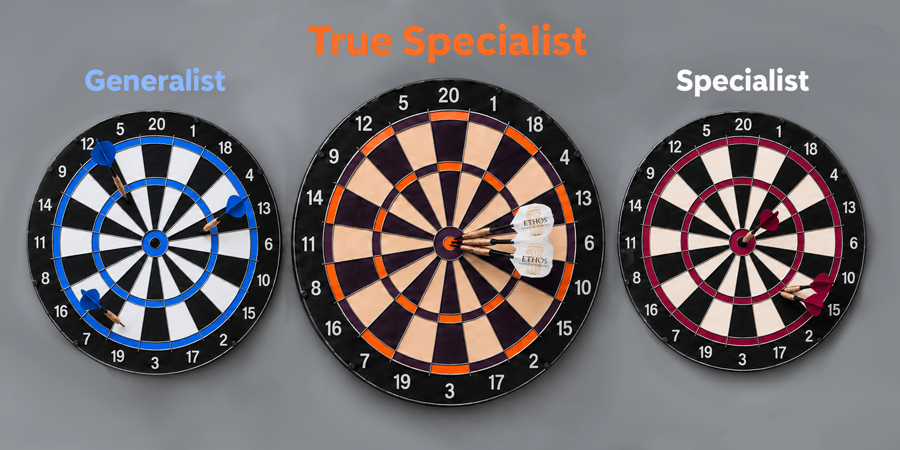
Unlike your typical generalist wholesaler and even wholesalers with a meaningful focus on the healthcare space, a true HPL specialist wholesaler does much more than simply obtain quotes. They utilize their experience and expertise to assist their retail customers through the entire placement process:
Identify all exposures that need covered:
Because a true specialist has seen just about every risk profile there is, identifying all applicable professional exposures is akin to putting on an old hat—there’s very little chance of encountering something they haven’t seen before. This sets the stage for a successful placement.
Anticipate underwriting issues:
It is because a true specialist has seen it all that they have a deep understanding of what underwriters’ concerns will be and what they’ll need to get comfortable with a risk. A proactive assessment like this streamlines the placement process and saves time.
Present the risk in its best possible light to the marketplace:
Understanding the critical elements of any risk profile allows a true specialist to effectively present any risk profile to the marketplace in such a way that it sets the stage for success rather than delays and failure.
Negotiate the best placement terms:
A true specialist not only thoroughly knows each applicable carriers’ form/endorsements and has a solid feel for their appetite, but they also understand each carriers’ flexibility when it comes to the extension of coverage for various kinds of exposures and the probable pricing associated with each. This allows for a give and take negotiation that results in the best terms available.
Eliminate unnecessary quote/binding subjectivities:
It is precisely a true specialist’s understanding of what each carrier needs that allows them to identify and eliminate any unnecessary quote or binding subjectivities that an underwriter may have included in error or otherwise just doesn’t need.
Assist with quote option evaluation:
Once all carrier responses are in a true specialist has the knowledge and expertise to efficiently provide the applicable coverage highlights of each competitive proposal so you and your client can easily understand the pros and cons of each.
And let’s not forget the importance of service. When it comes to service, it doesn’t get any better than what you will receive from a true specialist. Why? Because when you do just one thing you must do it better than anyone else or you stand to lose everything. That’s a powerful motivator to provide prompt, responsive service day in and day out.
In short, the true HPL specialist wholesaler is the specialist, so you don’t need to be.
Work With a True HPL Specialist

At Ethos, healthcare professional liability (HPL) is not one of many things we do like most wholesale organizations. It is all we do.
Every member of our team operates exclusively in the HPL space. It is that singular focus that allows us to provide retail agents with a level of expertise, advocacy, and market insight that other wholesalers don’t have, and that HPL accounts demand.
If you have healthcare accounts, you need a wholesale partner that lives and breathes HPL every single day. Give us a call, and we’ll show you the difference a true specialist wholesaler like Ethos can make for you and your healthcare clients.
Click to Call, Email, or Schedule a Meeting now!